← Retour aux projets
RISING STONE - LA TARENTAISE
HO
Homunity Property development Financé
Ce projet est clôturé. L'analyse ci-dessous reflète les informations disponibles au moment de la souscription et n'a pas été mise à jour.

RISING STONE - LA TARENTAISE

Very Strong
77
score / 100
Yield
11.0%/yr
Duration
24 months
Min. ticket
1 k€
Amount raised
3.1 M€
Invest →
À propos

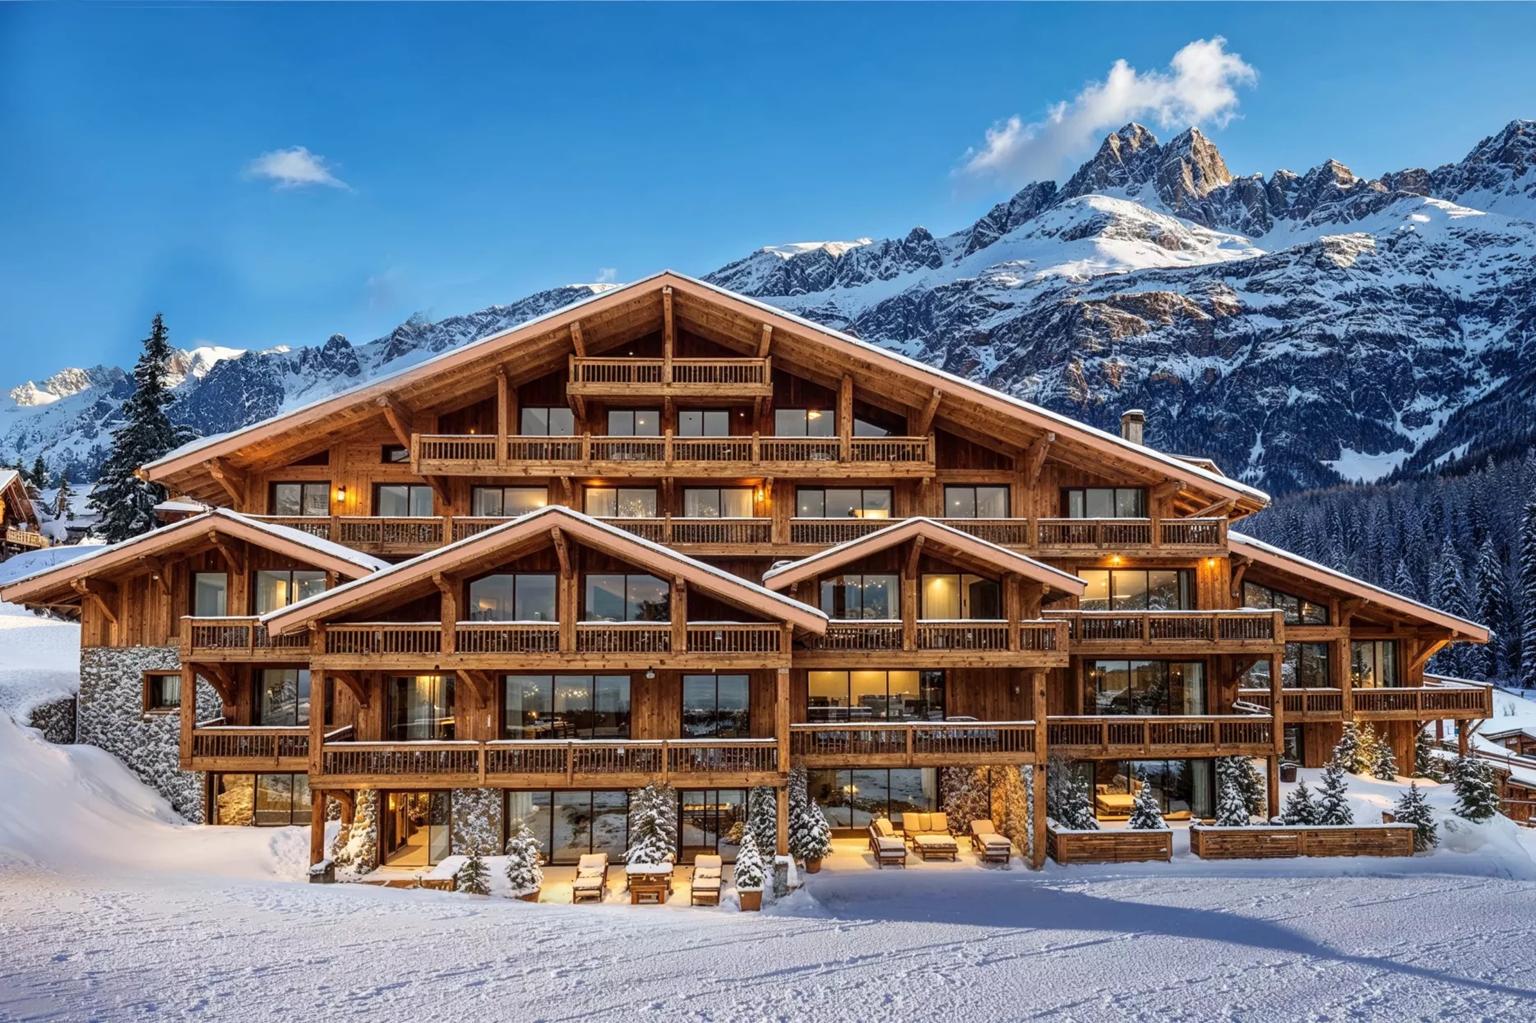
Equity refinancing for real estate promotion of 24 apartments (T2 to T5) in Meribel (73), demolition/reconstruction operation by Rising Stone. Land secured, building permit purged, start of works May 2026. Pre-marketing 57% in volume.

Plateforme · 17.0/25
A1 · Statut réglementaire 8.0/8✓ max
  • agrément AMF AMF fonds propres-2023-31 obtained on 9 November 2023, in force
  • CIF and COA status registre ORIAS 16003112
  • Member of France FinTech and CNCEF
A2 · Track Record 3.0/6
  • Score adjusted thanks to live data: Default rate 0.0% → 6/6×0.5=3.0
  • Delay rate 33.98% → 0/6×0.3=0.0
  • Actual yield 10.16% compliant with announced range → 6/6×0.2=1.2
  • Weighted: (3.0+0.0+1.2)=4.2, but penalty −2 pts for significant deterioration: 110/112 projects in delay, 80 in collective insolvency proceedings, target IRR decline
A3 · Rigueur de sélection 2.0/4
  • Selection process via internal committee mentioned
  • Selection rate not published
  • Financial analysis present in files
A4 · Santé financière 3.0/4bon
  • Score adjusted thanks to live data: Tikehau Capital subsidiary (50bn€ AUM), solid institutional group
  • BUT net loss SAS Homunity −2.24m€ (2024) vs −12.5k€ (2023), fundraising −66.46% (2022-2025)
  • Platform risk moderate but no imminent distress
A5 · Protection investisseurs 1.0/3faible
  • Reflection period 4 days + documented BCP Capsens → 1 pt (mandatory agrément AMF)
  • Segregated accounts not mentioned → 0 pt
  • Secondary market not documented → 0 pt
Projet · 60.0/75
B1 · Instrument & Structure 9.0/10bon
B1.1: 5/5 - Simple bond at fixed rate, French law
B1.2: 2/3 - Direct borrowing from operator Rising Stone, well documented
B1.3: 2/2 - No documented subordination, simple bond without known senior debt
B2 · Opérateur & Track record 13.0/15bon
B2.1: 4/4 - Jean-Thomas Olano appointed, CEO publicly identifiable
B2.2: 5/5 - Group created 2013, Euronext Growth IPO February 2026, turnover 71.2M€, net result 9.8M€, 18.1M€ cash
B2.3: 3/3 - 7 operations reimbursed without delay on Homunity, 5 in progress without incident
B2.4: 1/3 - Adjusted score thanks to live data: No collective insolvency proceeding identified on Rising Stone or JTO Holding. Sound balance sheets. BUT high gearing: (161.3-45.4)/45.4=2.55
B3 · Garanties & Sûretés 9.0/15
B3.1: 5/9 - Joint and several guarantee from JTO Holding, capitalised holding, no registered real guarantee
B3.2: 2/4 - JTO Holding: equity 45.4M€, gearing 2.55 (tight but operational situation)
B3.3: 2/2 - Bank credit 16.5M€ granted
B4 · Structure financière 13.0/15bon
B4.1: 5/5 - Loan-to-Cost (ratio prêt/coût total) calculated: 3.13M€/(49.996M€)=6.3% (cost covered at 115% by current sales plus bank plus equity plus Homunity)
B4.2: 4/4 - Operator equity 4.87M€ on 49.996M€ total TTC = 9.7%, close to 10%
B4.3: 2/4 - Scenario -30% on stock units: real estate cash flow remains positive at 5.0% of turnover TTC
B4.4: 2/2 - Net margin 11.4% plus real estate cash flow 16.4% of turnover TTC
B5 · Pré-commercialisation 8.0/10bon
  • 57% in volume pre-marketed by reservations and agreements, of which 8 units out of 14 reserved
  • Majority in reservation (non-binding), remaining 6 units to sell
  • Break-even well exceeded
B6 · Permis & Maturité 5.0/5✓ max

Land secured, building permit obtained and purged, construction site rules and delivery notes obtained, general assessment obtained, building site scheduled May 2026

B7 · Marché & Localisation 3.0/3✓ max
  • Adjusted score thanks to live data: Meribel premium market (Three Valleys), supply below documented structural demand, demand 9% above supply in Tarentaise
  • Target prices 26K-35K€/m² consistent with high-end market (11.8-19.8K€/m² prestige segment, chalets >8K€/m²)
Points forts
✓Euronext Growth listing February 2026, fundraising 35.5M€.
✓Experienced operator: 7 projects reimbursed without delay on Homunity.
✓Pre-marketing 57% before start of works, operation cost covered at 115%.
✓Land secured, permit purged, premium Meribel market in Three Valleys.
✓Bank credit 16.5M€ obtained, identified financial partner.
✓Margin 11.4% and real estate cash flow 16.4% of turnover TTC.
✓Stress scenario -30% on stock units: cash flow remains positive at 5.0%.
✓Financial guarantee for completion obtained to secure delivery.
Risques identifiés
!High JTO Holding gearing at 2.55, pressure on guarantor financial structure.
!6 units remaining to market over 24 months, including 4 high-end T5 units.
!High mountain building site: limited work window 7 months/year May-November.
!No registered real guarantee, only joint and several guarantee without identified collateral.
!Homunity platform: 110/112 projects in delay, 33.98% delay rate by amount.
!Homunity net loss -2.24M€ in 2024, fundraising -66.46% 2022-2025.
!Climate: risks of snowfall medium-long term on attractiveness of alpine resorts.
!Exit price T5 prestige 30-38K€/m², demanding high-end segment in liquidity.
⚠ Avertissement sur les risques

Investir en crowdfunding comporte un risque de perte partielle ou totale du capital, ainsi qu'un risque d'illiquidité. Selon le baromètre France FinTech / Forvis Mazars 2025, 25 à 30 % des projets accusent un retard de plus de 6 mois et 4 à 6 % entraînent une perte définitive. Ne placez jamais plus de 5 à 10 % de votre patrimoine en crowdfunding et diversifiez sur au moins 10 projets. CrowdPickr est un service d'information indépendant, non agréé en tant que conseiller en investissement. Les analyses présentées ne constituent pas un conseil en investissement personnalisé.