← Retour aux projets
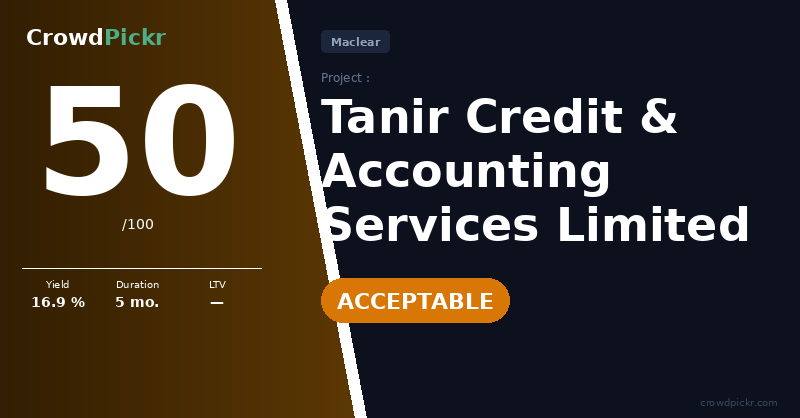
Tanir Credit & Accounting Services Limited
MA
Maclear Business lending Financé
Ce projet est clôturé. L'analyse ci-dessous reflète les informations disponibles au moment de la souscription et n'a pas été mise à jour.

Tanir Credit & Accounting Services Limited

Average
50
score / 100
Yield
16.9%/yr
Duration
5 months
Min. ticket
—
Amount raised
50 k€
Invest →
À propos

Loan of €50,000 (tranche of total revolving facility of €3.5M) to Tanir Credit & Accounting Services Limited, a digital credit institution based in Kenya (Nairobi/Mombasa), founded in 2018 and licensed by the Central Bank of Kenya since October 2024. The operator issues B2C microloans and B2B/factoring loans, with 85,000+ loans issued per year. Bullet obligation over 5 months at 16.9% p.a., with monthly interest.

Plateforme · 9.0/25
A1 · Statut réglementaire 3.0/8faible
  • Swiss platform, outside AMF/agrément AMF/ECSP
  • SRO supervision PolyReg (self-regulation) with FINMA as ultimate backstop
  • Functional equivalent but inferior to agrément AMF/ECSP or FSC/BaFin licence
  • No European passport
  • Score aligned on registration only without agrément AMF licence
A2 · Track Record 3.0/6
  • Stated default rate 0.1% (<1% → 6 pts base)
  • Delay rate >90 days not published → N/C → 0 pts
  • Real yield vs announced yield not verifiable (no audited report 2024) → N/C → 0 pts
  • Gross score: (6×0.5 + 0×0.3 + 0×0.2) = 3.0
  • No -2 penalty as default rate partially published
A3 · Rigueur de sélection 1.0/4faible
  • Selection rate not published
  • Process not documented publicly
  • Two documented cases of fraud/false information to investors (Estlat, Vibroedil) calling into question the rigour of the process
  • Established platform recognised in its niche but proven deficient selection
A4 · Santé financière 1.0/4faible
  • No audited financial report 2024 published (March 2026, delay justified by migration)
  • Small reserve fund and not transparent
  • Target yields 20%+ without verifiable solvency reserves
  • 720% growth but suspect business model
  • No active distress signal but insufficient transparency for 2+ pts
A5 · Protection investisseurs 1.0/3faible
  • No agrément AMF/ECSP licence → automatic 1 pt rule not applicable
  • SRO PolyReg offers minimal framework
  • Reserve fund existing but opaque and undersized
  • No documented secondary market
  • No segregated account publicly confirmed
  • 1 pt for SRO framework
Projet · 41.0/75 (44.0 brut, red flags −3)
B1 · Instrument & Structure 7.0/10
B1.1: 5/5 - Simple obligation at fixed rate 16.9% p.a., clear rights
B1.2: 1/3 - Direct loan from Kenyan operator, non-EU local law, applicable law poorly documented
B1.3: 1/2 - Rank not formally registered, no documented known senior debt
B2 · Opérateur & Track record 9.0/15
B2.1: 4/4 - CEO Leah Muthoni Nganga appointed, role specified, detailed management structure
B2.2: 3/5 - NBFI licensed by CBK >2 years, 85,000+ loans/year, structured digital model but outside EU zone
B2.3: 1/3 - First transaction on Maclear, reputation not verifiable on other AMF platforms
B2.4: 1/3 - Healthy and growing balance sheets, but CBK licence recent (Oct. 2024), legal file not verifiable on Kenyan registers
B3 · Garanties & Sûretés 6.0/15faible
B3.1: 4/9 - Personal guarantee from director (not notarised) + pledge of loan portfolio and assets (€1,999,842 declared value)
B3.2: 1/4 - Guarantor CEO with no verifiable declared assets; dynamic collateral (portfolio) not formally registered
B3.3: 2/2 - NBFI licensed by CBK operating >2 years: sufficient institutional quality per SME-NBFI rule
B4 · Structure financière 11.0/15
B4.1: 4/5 - Estimated taux de couverture de la dette >2.0 (target ICR ≥2.0x, net profit €593K over 9 months, debt €50K)
B4.2: 3/4 - Operator equity present via re-lending; acknowledged liquidity constraint, no equity/asset ratio explicitly provided
B4.3: 3/4 - Margins in constant increase, -20% stress absorbable given 27% net margin
B4.4: 1/2 - Excellent 27% net margin but loan to emerging NBFI outside EU with FX risk
B5 · Pré-commercialisation 6.0/10
  • Active portfolio 85,000 loans/year, B2C/B2B/factoring diversification, history since 2018
  • Portfolio data available but B2C concentration 67% and individual default rate 13% elevated
  • Score: 6/10 active portfolio with correct diversification, partial history
B6 · Permis & Maturité 4.0/5bon
  • Licence DCP CBK/DCP/2024/82 in force since Oct
  • Sound legal structure, supervised fees paid up to date
  • Recent licence (<2 years) justifies slight caution
  • Score: 4/5
B7 · Marché & Localisation 1.0/3faible
  • Kenyan digital lending market in growth (estimated 20-23% CAGR)
  • NPL rate ~9.3% (>10% alert threshold)
  • Market outside France, EUR/KES FX risk, emerging regulation
  • Score: 1/3 secondary market in development, regulatory and FX uncertainties
⚠ Alertes détectées · −3 pts déduits
Rendement élevé sans garantie réelle −3 pts

Rate served 16.9%/year without registered real guarantee (Kenyan portfolio pledge not formally registered, personal guarantee not notarised)
Points forts
✓Constant profitability growth 2021-2024: net margin increased from 7.9% to 27%.
✓CBK licence in force, Kenyan regulatory framework maturing.
✓Revolving portfolio 85,000+ loans/year, strong B2C/B2B/factoring diversification.
✓Liquidity reserve (DSRA 3 months interest) and segregated accounts planned.
✓Factoring default rate 1%, B2B 2%: higher quality segments in growth.
Risques identifiés
!EUR/KES exchange rate risk not hedged: Kenyan shilling depreciation weighs on repayment.
!B2C individual default rate 13%: 67% portfolio concentration on riskiest segment.
!Collateral mainly constituted by Kenyan loan portfolio not formally registered in Europe.
!Maclear platform: documented cases of fraud on previous projects (Estlat, Vibroedil), deficient selection.
!CBK licence very recent (Oct. 2024); previously operated without formal licence during prolonged transition period.
⚠ Avertissement sur les risques

Investir en crowdfunding comporte un risque de perte partielle ou totale du capital, ainsi qu'un risque d'illiquidité. Selon le baromètre France FinTech / Forvis Mazars 2025, 25 à 30 % des projets accusent un retard de plus de 6 mois et 4 à 6 % entraînent une perte définitive. Ne placez jamais plus de 5 à 10 % de votre patrimoine en crowdfunding et diversifiez sur au moins 10 projets. CrowdPickr est un service d'information indépendant, non agréé en tant que conseiller en investissement. Les analyses présentées ne constituent pas un conseil en investissement personnalisé.