← Retour aux projets
Servis Logistic and Outsourcing
MA
Maclear Business lending Financé
Ce projet est clôturé. L'analyse ci-dessous reflète les informations disponibles au moment de la souscription et n'a pas été mise à jour.

Servis Logistic and Outsourcing

Average
61
score / 100
Yield
14.5%/yr
Duration
14 months
Min. ticket
—
Amount raised
500 k€
Invest →
À propos

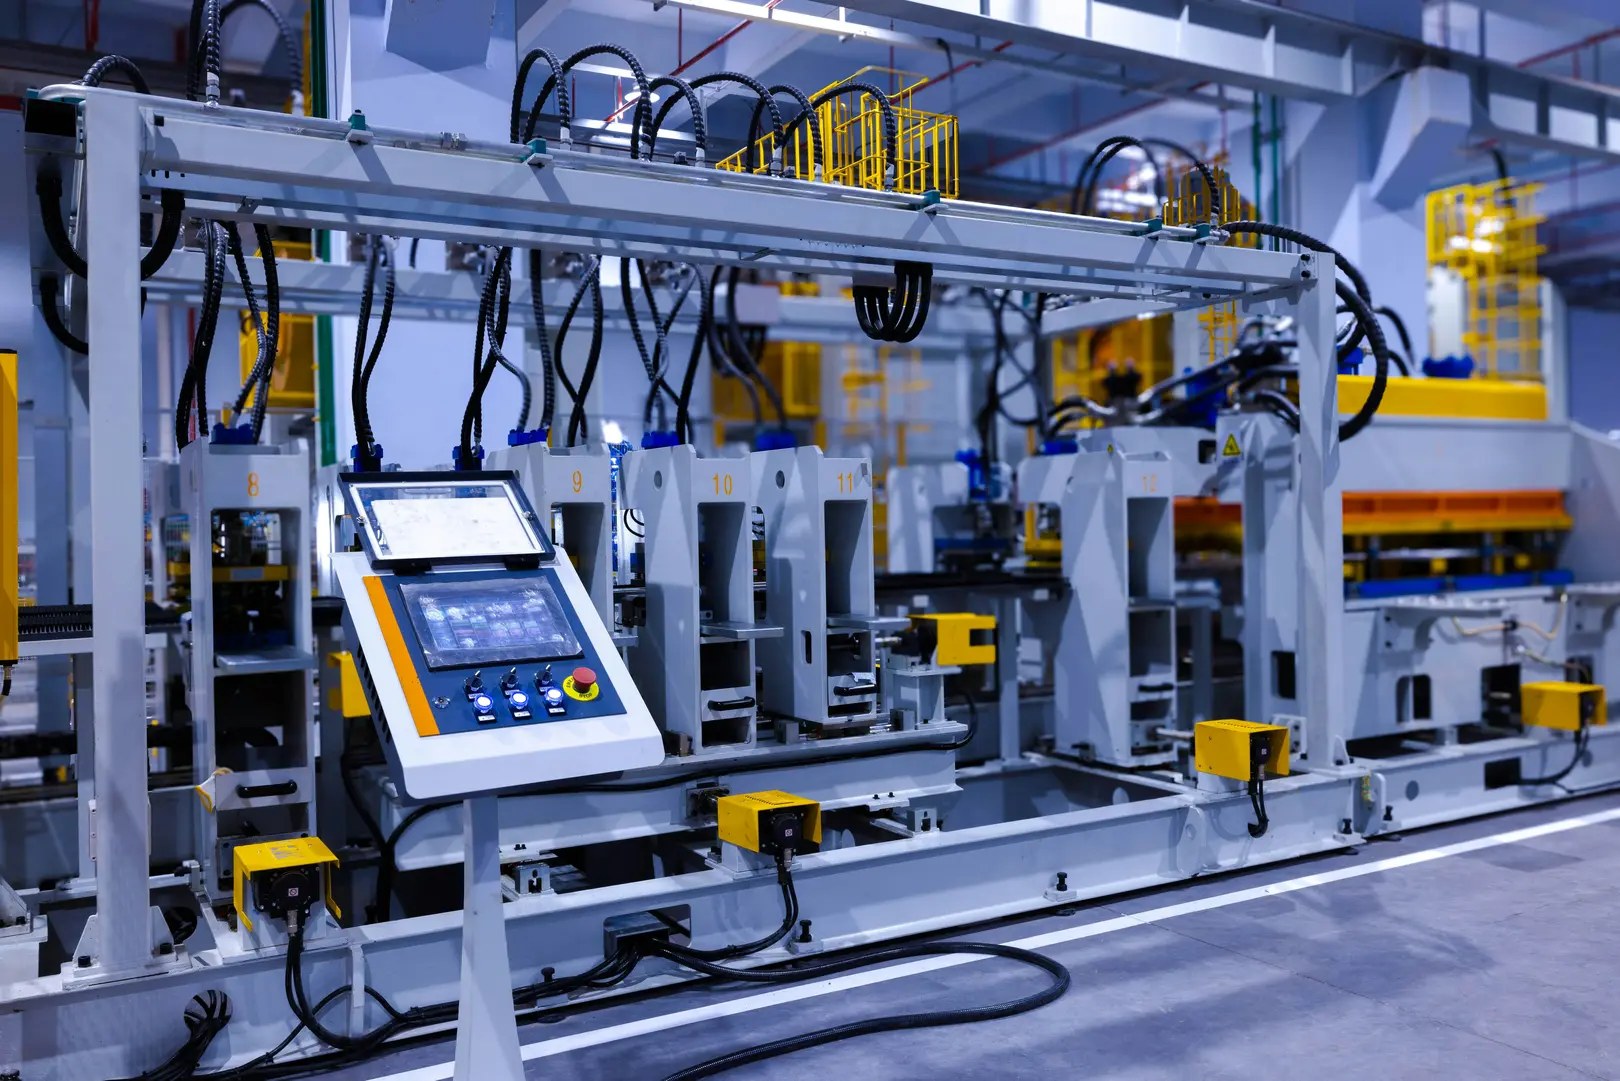
Loan of €500,000 to Servis Logistic and Outsourcing s.r.o., Czech intralogistics systems integrator based in Liberec (Czech Republic), to finance equipment purchase under two signed contracts (Novanta Medical and TREVOS). Company in operation since 2016, balance sheet without external debt at facility entry. In fine structure over 14 months at 14.5%/year.

Plateforme · 9.0/25
A1 · Statut réglementaire 3.0/8faible
  • Swiss platform, outside AMF/agrément AMF/ECSP
  • SRO supervision PolyReg (self-regulation) with FINMA as ultimate backstop
  • Functional equivalent but inferior to agrément AMF/ECSP or FSC/BaFin licence
  • No European passport
  • Score aligned on registration only without agrément AMF licence
A2 · Track Record 3.0/6
  • Stated default rate 0.1% (<1% → 6 pts base)
  • Delay rate >90 days not published → N/C → 0 pts
  • Real yield vs announced yield not verifiable (no audited report 2024) → N/C → 0 pts
  • Gross score: (6×0.5 + 0×0.3 + 0×0.2) = 3.0
  • No -2 penalty as default rate partially published
A3 · Rigueur de sélection 1.0/4faible
  • Selection rate not published
  • Process not documented publicly
  • Two documented cases of fraud/false information to investors (Estlat, Vibroedil) calling into question the rigour of the process
  • Established platform recognised in its niche but proven deficient selection
A4 · Santé financière 1.0/4faible
  • No audited financial report 2024 published (March 2026, delay justified by migration)
  • Small reserve fund and not transparent
  • Target yields 20%+ without verifiable solvency reserves
  • 720% growth but suspect business model
  • No active distress signal but insufficient transparency for 2+ pts
A5 · Protection investisseurs 1.0/3faible
  • No agrément AMF/ECSP licence → automatic 1 pt rule not applicable
  • SRO PolyReg offers minimal framework
  • Reserve fund existing but opaque and undersized
  • No documented secondary market
  • No segregated account publicly confirmed
  • 1 pt for SRO framework
Projet · 52.0/75
B1 · Instrument & Structure 8.0/10bon
B1.1: 5/5 - Simple bond at fixed rate 14.5%, clear entitlement
B1.2: 2/3 - Direct loan from operator (Czech SRO), recognised EU local law entitlement
B1.3: 1/2 - Priority rank claimed, pledge of equipment documented but not formally registered
B2 · Opérateur & Track record 9.0/15
B2.1: 4/4 - Zdeněk Palisch named, born 12/07/1961, CEO and sole identifiable shareholder
B2.2: 2/5 - SME established >5 years, stable sector, proven growth but not regulated NBFI
B2.3: 1/3 - First operation on Maclear, reputation not verified elsewhere
B2.4: 2/3 - Healthy balance sheet, zero debt, D/E 1.97 post-facility tight but acceptable
B3 · Garanties & Sûretés 9.0/15
B3.1: 5/9 - Pledge of equipment (€567K invoice value) + CEO personal guarantee €100K; hard collateral Loan-to-Value (ratio prêt/valeur actif) 0.85, total Loan-to-Value (ratio prêt/valeur actif) 0.72
B3.2: 1/4 - fonds propres €253K, gearing 1.97 post-facility, limited capital base
B3.3: 2/2 - SME-NBFI: borrower licensed or institutional not required; signed validated contracts = sufficient institutional quality
B4 · Structure financière 13.0/15bon
B4.1: 4/5 - taux de couverture de la dette 2026F: (82,567+42,292)/42,292 = 2.95× → taux de couverture de la dette 2.0-2.5 → 4 pts
B4.2: 3/4 - Equity €253K vs facility €500K, own contribution ~33% of operational capital
B4.3: 4/4 - ICR 2.95× in 2026F, scenario -30% turnover maintains interest coverage; zero pre-existing debt
B4.4: 2/2 - Net margin 6.9% (2025), taux de couverture de la dette >2.0
B5 · Pré-commercialisation 6.0/10
  • SME-NBFI: active portfolio €2.64M across 10 counterparties
  • Two firm signed contracts (€886K) directly financing the loan
  • Three contracts in performance (€559K)
  • LOI €1.19M not contractualised
  • Correct diversification, partial history
B6 · Permis & Maturité 5.0/5✓ max

Activity established since 2016 (>2 years), ICO 05078407 registered, all legal documents in order, valid licences, Czech company in continuous operation

B7 · Marché & Localisation 2.0/3
  • Score adjusted thanks to live data: European intralogistics market in strong growth (CAGR 9-18%), robust CEE nearshoring
  • Alternative SME lending market France/EU stable but NPL rates and credit standards tightening slightly
  • Established market, 2/3 appropriate
Points forts
✓Debt-free balance sheet on facility entry, zero pre-existing debt documented.
✓Two firm signed contracts (€886K) directly backing the loan.
✓Revenue growth x3 in 3 years with maintained profitability.
✓Equipment collateral at 96.4% principal coverage in liquidation.
✓ICR 2.95× in 2026F, solid monthly interest coverage.
Risques identifiés
!Key-person concentration: CEO sole shareholder and director, high operational risk.
!Limited equity base (€253K) against facility of €500K; D/E 1.97 post-debt.
!In fine repayment depends on customer settlement on site acceptance - calendar risk.
!Maclear platform: documented cases of fraud on past projects (Estlat, Vibroedil).
!Pledge of equipment not formally registered; CEO personal guarantee limited to €100K.
⚠ Avertissement sur les risques

Investir en crowdfunding comporte un risque de perte partielle ou totale du capital, ainsi qu'un risque d'illiquidité. Selon le baromètre France FinTech / Forvis Mazars 2025, 25 à 30 % des projets accusent un retard de plus de 6 mois et 4 à 6 % entraînent une perte définitive. Ne placez jamais plus de 5 à 10 % de votre patrimoine en crowdfunding et diversifiez sur au moins 10 projets. CrowdPickr est un service d'information indépendant, non agréé en tant que conseiller en investissement. Les analyses présentées ne constituent pas un conseil en investissement personnalisé.