← Retour aux projets
Portefeuille Hôtels Sociaux - JLS
BR
Bricks Commercial real estate Financé
Ce projet est clôturé. L'analyse ci-dessous reflète les informations disponibles au moment de la souscription et n'a pas été mise à jour.

Portefeuille Hôtels Sociaux - JLS

Average
52
score / 100
Yield
9%/yr
Duration
48 months
Min. ticket
10 €
Amount raised
1.1 M€
Invest →
À propos

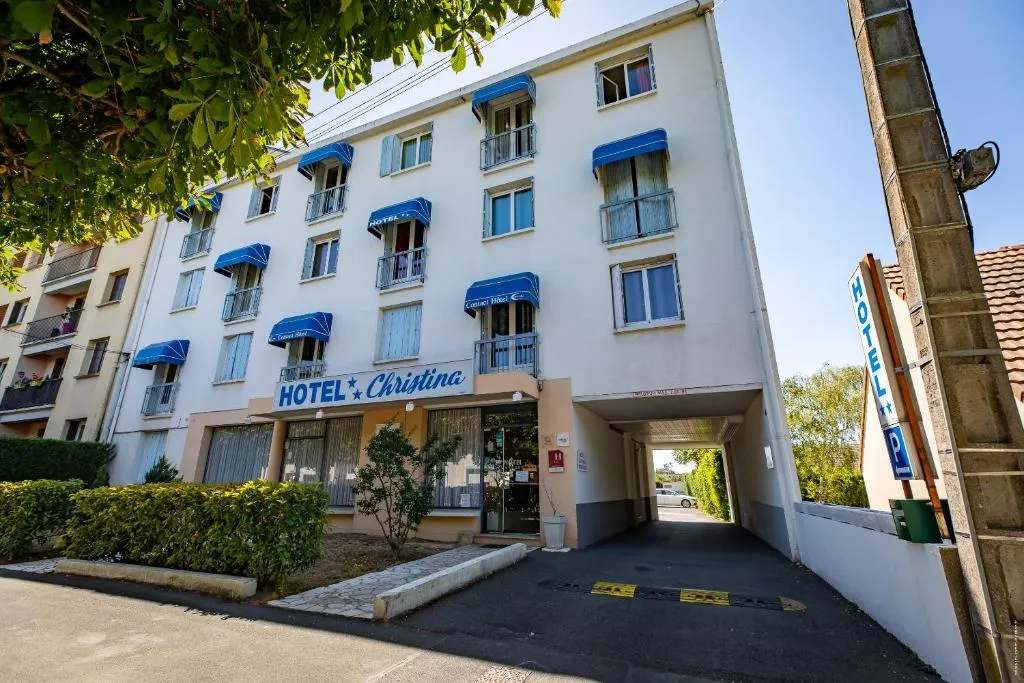
Obligatory bond financing of 1,098,000€ for acquisition of five hotel business transfers (social accommodation) located in Chateauroux, Saverne, Rennes and Toulouse. Issuer JLS (Jean-Luc Cohen & Laurent Abadi-Bousbaci) raises funds via Bricks to finance its contribution share as current account capital in acquisition company GROUPE H.E.S. Main security is first ranking pledge over hotel business ZYNND (Paris 1st arrondissement, acquired outright 1,160,000€ in April 2025). Duration 24-48 months, rate 9% per annum paid monthly.

Plateforme · 19.0/25
A1 · Statut réglementaire 8.0/8✓ max
  • agrément AMF licence in valid force, fonds propres-2023-8 licence
  • Maximum applicable score
A2 · Track Record 5.0/6bon
  • Default 0% → 6/6
  • Delay 5.38% (threshold 5-15%) → 4.5/6
  • Net return 7.78% vs 10% announced, gap 2.22pp below lower bound → 1.5/6
  • Weighted score: (6×0.5)+(4.5×0.3)+(1.5×0.2)=4.65 → rounded 5
A3 · Rigueur de sélection 2.0/4
  • Selection process not detailed publicly, selection rate not published
  • Implicit mention of a process via agrément AMF licence
  • Score 2/4
A4 · Santé financière 2.0/4
  • Independent platform in strong growth (141M€, no.1 FR 2025)
  • Forced stoppage 7 months (Dec 2022-Jul 2023) and registre ORIAS deletion resolved
  • No identified institutional shareholder
  • Viability confirmed but regulatory history weighs
  • Score 2/4
A5 · Protection investisseurs 2.0/3
  • agrément AMF licenced → mandatory reflection period 4 days + Capsens continuity plan documented → 1 pt
  • Segregated accounts legally mandatory under agrément AMF → 1 pt
  • Secondary market not mentioned → 0 pt
Projet · 33.0/75 (38.0 brut, red flags −5)
B1 · Instrument & Structure 7.0/10
B1.1: 5/5 - Simple obligation fixed rate, clear French law
B1.2: 1/3 - Loan by JLS SAS, but funds transit via CCA to acquisition société dédiée (SPV) GROUPE H.E.S., multi-level structure lacks transparency
B1.3: 1/2 - No senior debt formally registered as at date, de facto ranking but not registered
B2 · Opérateur & Track record 7.0/15faible
B2.1: 3/4 - Jean-Luc Cohen and Laurent Abadi appointed with functions, partial verifiability
B2.2: 2/5 - One hotel asset held (ZYNND, 2025), documented hotel experience limited
B2.3: 0/3 - First operation on Bricks
B2.4: 2/3 - No insolvency procedure identified, JLS and holdings balance sheets partially documented
B3 · Garanties & Sûretés 8.0/15
B3.1: 6/9 - First ranking pledge over ZYNND funds (1.16M€, free of encumbrance), plus pledge of GROUPE H.E.S. shares (ranking uncertain vs senior), plus joint and several guarantees from holdings and personal guarantors
B3.2: 1/4 - GS HOLDING capital 1.14M€, gearing unknown; CMJL INVEST capital 360K€; balance sheets not provided
B3.3: 1/2 - Senior bank debt mentioned but bank unnamed and amount unfixed
B4 · Structure financière 9.0/15
B4.1: 3/5 - Crowd 1.098M€ / total cost 3.5M€ = Loan-to-Cost (ratio prêt/coût total) 31.4%, excellent
B4.2: 2/4 - Equity contribution by partners completes structure, exact amount not specified; senior bank debt principal
B4.3: 2/4 - ASE conventions in course of finalisation, revenues not yet contractualised; very low Loan-to-Cost (ratio prêt/coût total) partially offsets
B4.4: 2/2 - Target IRR not specified but social accommodation model has structural demand
B5 · Pré-commercialisation 3.0/10faible
  • Promhotel/Herbjotel conventions secured for 3 hotels; ASE conventions for 2 Chateauroux hotels in course of finalisation
  • No final signed lease presented
  • Social accommodation market has structural demand but contractual commitment partial
B6 · Permis & Maturité 2.0/5faible
  • Acquisition not yet completed (business transfer under implicit undertaking)
  • Prior declarations not mentioned
  • ZYNND funds acquired but portfolio hotels not yet formalised
B7 · Marché & Localisation 2.0/3
  • Score adjusted thanks to live data: ZYNND guarantee in Paris 1st arrondissement, rising Paris hotel market, record RevPAR H2 2025, occupancy 80.7%
  • Hotels operational in secondary cities (Chateauroux, Saverne) - more uncertain but diversified market
⚠ Alertes détectées · −5 pts déduits
Pas de financement bancaire −5 pts

Total operation amount 3.5M€ > 2M€ - senior bank unnamed, amount unfixed as at fundraising date
Points forts
✓Very low LTC (31%) on total operation cost 3.5M€
✓ZYNND guarantee Paris 1st arrondissement acquired outright 1.16M€, free of any encumbrance
✓Social accommodation: structural demand little dependent on tourism
✓First ranking pledge over business transfer plus pledge of acquisition SPV shares
✓Geographic diversification over 5 establishments in 4 cities
Risques identifiés
!ASE conventions for Chateauroux hotels in course of finalisation - revenues not yet contractualised
!Senior debt amount and bank unfixed as at date - ranking of future obligatory pledges uncertain
!Balance sheets of GS HOLDING and CMJL INVEST not provided - solidity of guarantors not verifiable
!First operation by Cohen/Abadi team at this scale - documented experience limited
!Funds transit via JLS → CCA → GROUPE H.E.S. → sellers: multi-level structure with dilution risks
⚠ Avertissement sur les risques

Investir en crowdfunding comporte un risque de perte partielle ou totale du capital, ainsi qu'un risque d'illiquidité. Selon le baromètre France FinTech / Forvis Mazars 2025, 25 à 30 % des projets accusent un retard de plus de 6 mois et 4 à 6 % entraînent une perte définitive. Ne placez jamais plus de 5 à 10 % de votre patrimoine en crowdfunding et diversifiez sur au moins 10 projets. CrowdPickr est un service d'information indépendant, non agréé en tant que conseiller en investissement. Les analyses présentées ne constituent pas un conseil en investissement personnalisé.