← Retour aux projets
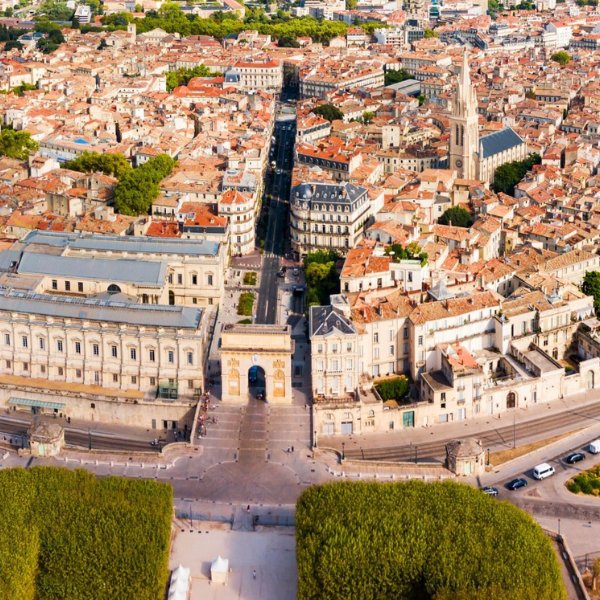
Polygone – Montpellier (34)
CL
ClubFunding Commercial real estate Financé
Ce projet est clôturé. L'analyse ci-dessous reflète les informations disponibles au moment de la souscription et n'a pas été mise à jour.

Polygone – Montpellier (34)

Average
50
score / 100
Yield
11%/yr
Duration
24 months
Min. ticket
—
Amount raised
680 k€
Invest →
À propos

Acquisition and renovation of 340 m² of offices (2 open spaces, 5th and 6th floors) at 265 avenue des États du Languedoc in Montpellier (Antigone district), for lease to independent health professionals. Operator JDB Group & HM Group plans division into 19 offices, lease implementation, then bank long-term refinancing to repay ClubFunding debt. Current stage: promise of sale signed, works upcoming (3 months), 8 offices under letter of intent.

Plateforme · 16.0/25
A1 · Statut réglementaire 8.0/8✓ max

AMF agrément AMF licence in force → 8 pts

A2 · Track Record 1.0/6faible
  • Default 17.45% (>15%) → 0/6
  • Delay rate 31.05% (30-50%) → 1.5/6
  • Realised return 6.5-7.5% vs announced ~10% (gap ~2.5-3.5pp below lower bound) → 1.5/6
  • A2 = (0×0.5)+(1.5×0.3)+(1.5×0.2) = 0.75 → rounded 1/6
A3 · Rigueur de sélection 2.0/4

Ranked 5th in 2024 rankings, process mentioned, but selection rate not published and concerns flagged on selection quality

A4 · Santé financière 3.0/4bon

Independent platform, active since 2014, >€1bn raised, monthly publication of indicators, no platform distress signal identified

A5 · Protection investisseurs 2.0/3
  • Licensed agrément AMF → reflection period 4 days + continuity plan (1 mandatory pt)
  • Standard agrément AMF segregated accounts (1 pt)
  • Secondary market not documented (0 pt)
Projet · 34.0/75 (39.0 brut, red flags −5)
B1 · Instrument & Structure 8.0/10bon
B1.1: 5/5 - Simple bond fixed rate, French law
B1.2: 2/3 - Dedicated société dédiée (SPV) SAS MAGNOLIA POLYGONE, well documented
B1.3: 1/2 - First-rank mortgage mentioned but land not yet executed (promise)
B2 · Opérateur & Track record 7.0/15faible
B2.1: 2/4 - Directors appointed (BARBIER, MANSCOUR), no confirmed LinkedIn profile
B2.2: 2/5 - 1 Magnolia operation delivered, limited experience
B2.3: 2/3 - 1 operation repaid on ClubFunding
B2.4: 1/3 - Companies created Jan 2025, SAS MAGNOLIA created Sept 2026, capital €1,000, incomplete accounts
B3 · Garanties & Sûretés 11.0/15
B3.1: 7/9 - First-rank mortgage in process of registration (land under promise)
B3.2: 2/4 - Personal guarantees by BARBIER and MANSCOUR, patrimony not detailed
B3.3: 0/2 - No banking partner identified, project <€2m so no RF2
B4 · Structure financière 5.0/15faible
B4.1: 0/5 - Loan-to-Value (ratio prêt/valeur actif) crowd/asset value ~93% (€680k/€730k) exceeds 80% RE-COM threshold
B4.2: 0/4 - Operator equity quasi-zero (capital €1,000)
B4.3: 2/4 - Conservative scenario (75% occupancy) covers €700k refinancing taux de couverture de la dette 100%
B4.4: 1/2 - Implicit rental IRR uncertain, target rental return ~24%
B5 · Pré-commercialisation 4.0/10faible
  • 8 offices out of 19 under letter of intent (Rank 4, non-binding) + 15 verbal indications of interest
  • Magnolia reference 100% occupied encouraging
  • No firm commitment (lease or compromise) at this stage
B6 · Permis & Maturité 2.0/5faible
  • Acquisition not completed (promise signed April 2026, loan suspensive condition)
  • No administrative authorisation required for works
  • Pre-acquisition stage with works not started
B7 · Marché & Localisation 2.0/3
  • Montpellier, Antigone district, established market
  • Projected rents (€773/m²/year) above average (€512/m²/year) present absorption risk
  • Market stable per live data
⚠ Alertes détectées · −5 pts déduits
Ratio prêt/valeur trop élevé −5 pts

LTV calculated at ~93% (€680k crowd / ~€730k asset value) - 85% threshold exceeded on RE-COM asset
Points forts
✓First-rank mortgage registered on asset in process of formalisation
✓Magnolia reference: similar paramedical centre delivered, 100% occupied, valued €900k
✓Premium location Antigone district, well served (tramway, TGV)
✓Works escrow €460k and coupon reserve 18 months reduce misappropriation risk
✓Acquisition price very low (~€794/m²) creating safety margin on intrinsic value
Risques identifiés
!High crowd LTV (~93%) without documented operator equity contribution - total dependence on future bank refinancing
!Land not yet executed (promise with suspensive condition) - acquisition failure risk
!Projected rents (€773/m²/year) significantly above Montpellier market average (€512/m²/year) - absorption risk
!SAS MAGNOLIA POLYGONE created Sept 2026, capital €1,000 - vehicle without own financial foundation
!Exit dependent on bank refinancing not yet committed in a 3.65% rate environment
⚠ Avertissement sur les risques

Investir en crowdfunding comporte un risque de perte partielle ou totale du capital, ainsi qu'un risque d'illiquidité. Selon le baromètre France FinTech / Forvis Mazars 2025, 25 à 30 % des projets accusent un retard de plus de 6 mois et 4 à 6 % entraînent une perte définitive. Ne placez jamais plus de 5 à 10 % de votre patrimoine en crowdfunding et diversifiez sur au moins 10 projets. CrowdPickr est un service d'information indépendant, non agréé en tant que conseiller en investissement. Les analyses présentées ne constituent pas un conseil en investissement personnalisé.